Few advice markets test the Consumer Duty like equity release. The customers are older, the products last for life, interest compounds for decades, and the decision affects the family as well as the borrower. That makes evidencing good outcomes both more important and harder — especially if your evidence comes from a small sample of calls.
Why equity release gets closer scrutiny
Equity release combines several things the Consumer Duty cares about most. The products are long-term and hard to reverse. Interest usually rolls up and compounds, so the cost of a decision grows for years after it is made. Customers are more likely than most to have characteristics of vulnerability. And the effects reach beyond the borrower — to their estate, their family and their eligibility for means-tested benefits.
The FCA's reviews of equity release advice have repeatedly found weaknesses in how advice is personalised, how firmly advisers test customers' assumptions and how alternatives are considered. Those are exactly the things that happen — or don't — in the advice conversation.
What each outcome means for an equity release adviser
| Outcome | What to evidence on the call |
|---|---|
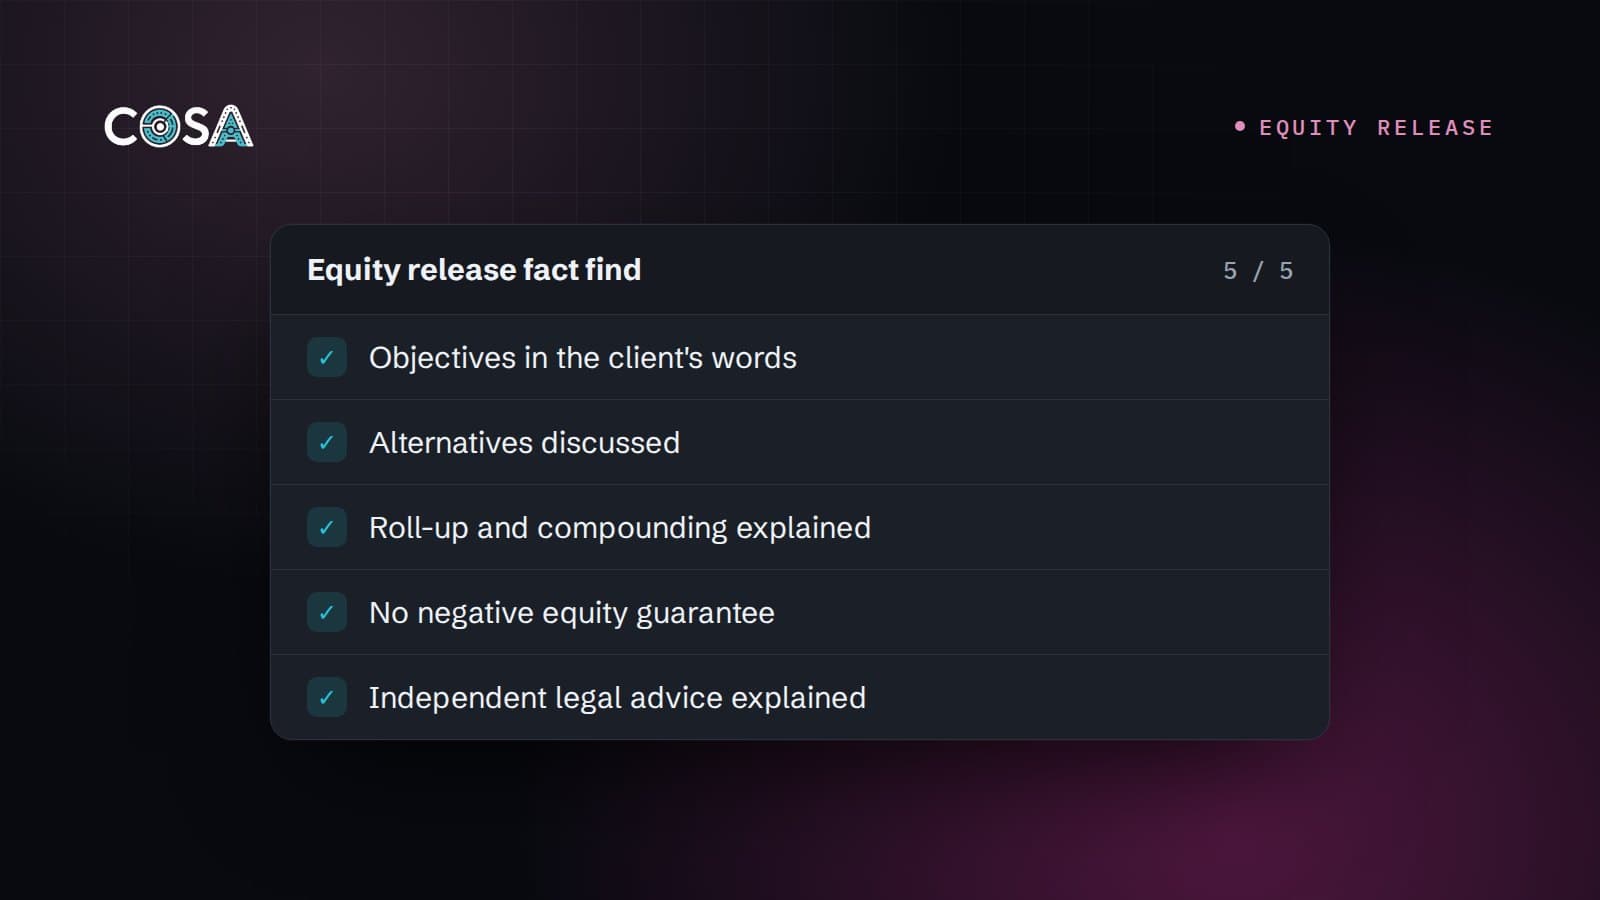
| Products & services | The customer's objectives in their own words; alternatives such as downsizing, savings, other borrowing, grants or family help discussed and the reasons for discounting them recorded. |
| Price & value | How interest roll-up and compounding work; fees; early repayment charges; the effect on what will be left in the estate. |
| Consumer understanding | The key features and protections explained in plain language, and the customer's understanding checked in their own words. |
| Consumer support | Signs of vulnerability noticed and handled; family involvement encouraged where the customer agrees; independent legal advice explained; clear next steps. |
For a point-by-point list, see our equity release advice call checklist.
The evidence gap in sampling
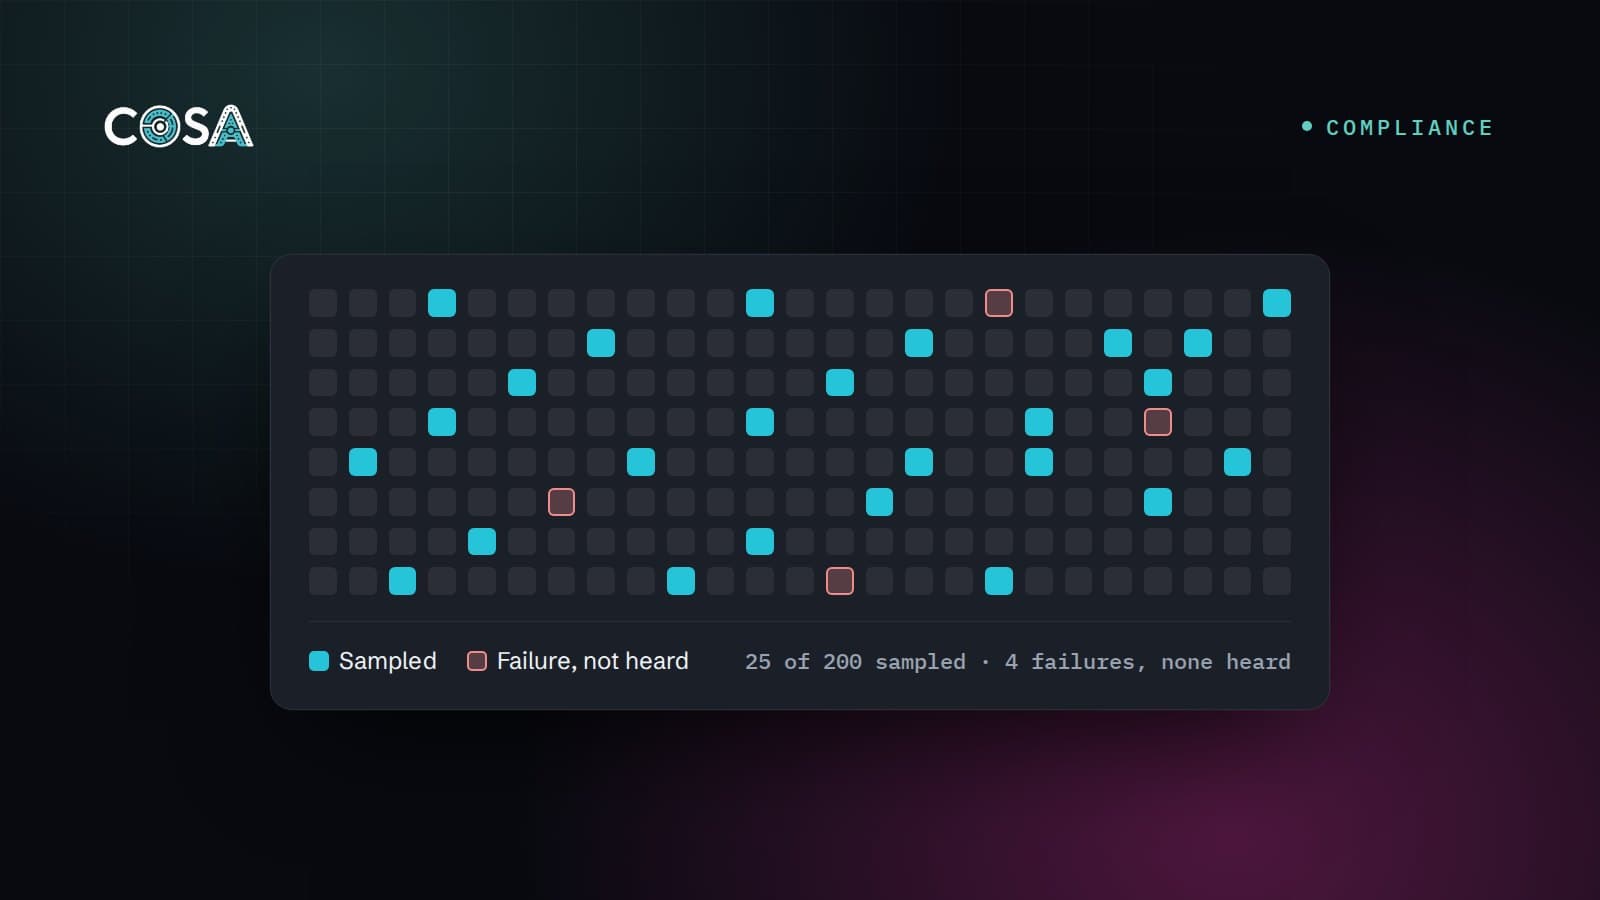
Suppose one fact find in fifty misses something important — the roll-up explanation, say, or a bereavement the adviser didn't pick up on. Review 25 calls at random and there is a 60% chance you won't hear a single one of them. Even at 100 calls, you'd miss them all more than one time in eight. The full calculation is in how many calls should you review?
The problem isn't that sampling is careless. It is that a sample can only tell you about the calls it covers — and under the Duty, the board is asked about all of them.
Building evidence from every advice call
- Encode your standards as rules — the recording notice word for word, and the topics that must be covered however they're phrased: alternatives, roll-up, protections, independent legal advice.
- Scope rules to call types. What must happen on a fact find differs from an initial enquiry or a follow-up.
- Assess every in-scope call, and log every excluded call with its reason.
- Review the flags — quickly, while there's time to follow up with the customer.
- Report by outcome, call type and adviser, with vulnerability as its own line.
- Act and record: coaching, remediation and rule changes, each with an owner.
What to put in the board report annex
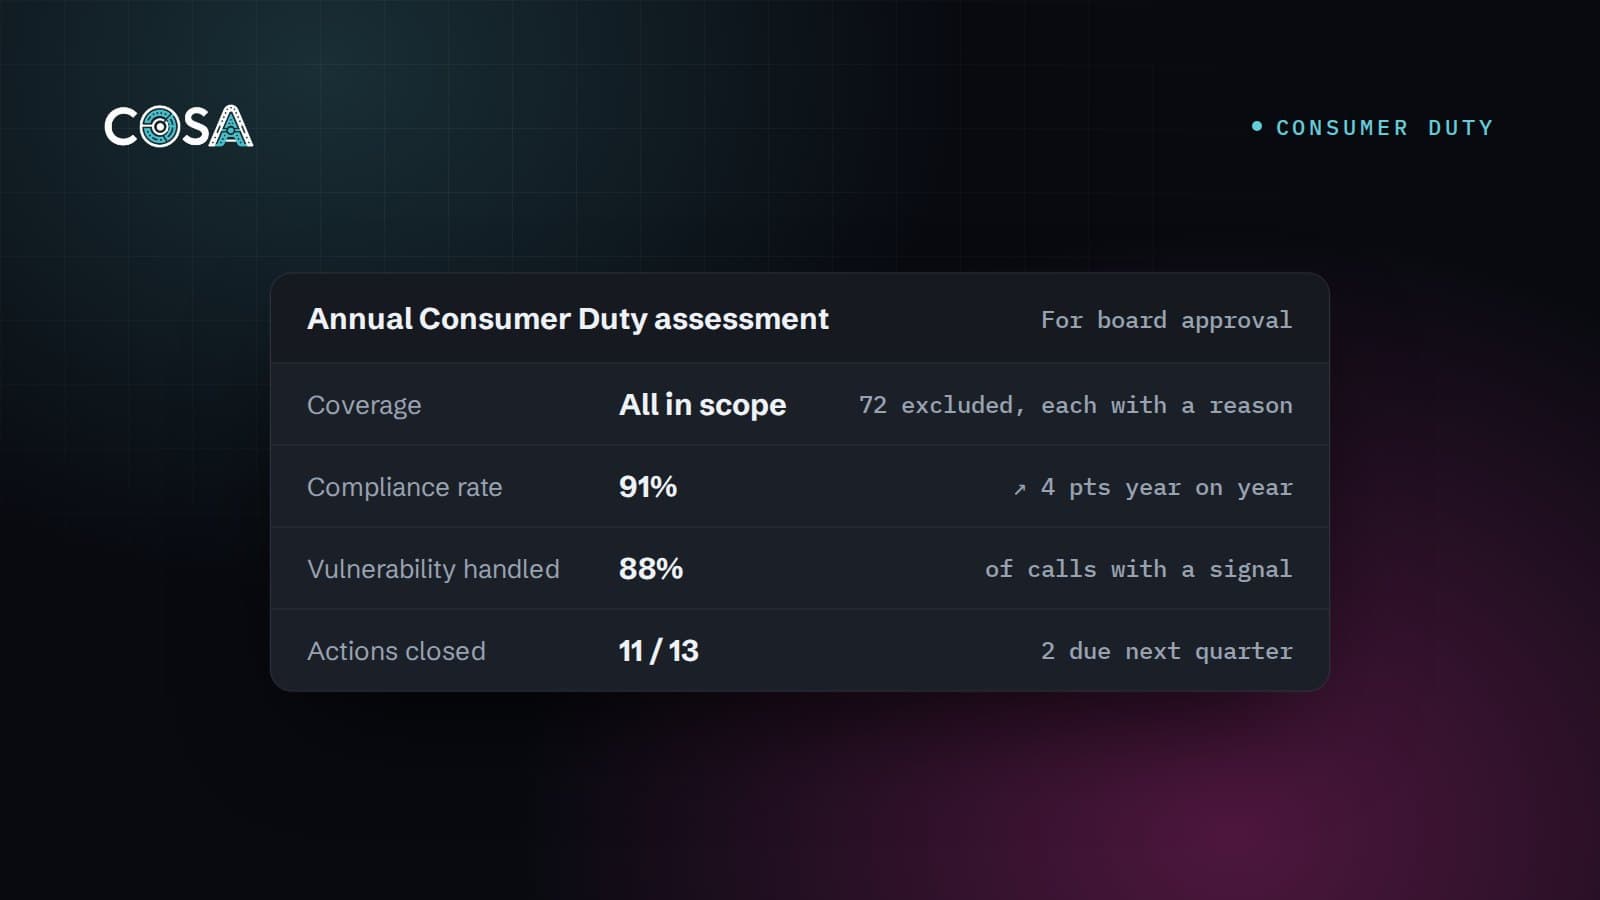
- Coverage: the calls assessed, and those excluded by reason.
- Compliance rate for each outcome, by call type, with twelve-month trends.
- The rules most often missed, with root causes and actions.
- Vulnerability: signals found by driver, handling rates, and outcomes compared with other customers.
- Reviewer overrides, and what they revealed about your rules.
- Progress on the actions agreed last year.
More on structure in what to put in your Consumer Duty board report.
What this looks like in practice
Compare Retirement, a phone-based equity release adviser working seven days a week, moved from manually sampling around 26% of calls to oversight of every client interaction — with QA on flagged calls taking minutes rather than hours. Read their story.
This article is general information, not legal or regulatory advice. Equity release may reduce the value of an estate and can affect entitlement to means-tested benefits.