The Consumer Duty changed the question regulators ask advice firms. It is no longer enough to have the right processes; you have to show that customers actually get good outcomes — and keep showing it, year after year.
What is the Consumer Duty?
The FCA introduced the Consumer Duty in its policy statement PS22/9 in July 2022. It came into force on 31 July 2023 for products and services open to sale or renewal, and on 31 July 2024 for closed products and services. It applies to firms across the distribution chain whose activities affect retail customers — including the advisers and brokers who speak to those customers every day.
At its centre is a new principle, Principle 12: "A firm must act to deliver good outcomes for retail customers." Where the Duty applies, it replaces Principles 6 and 7 (customers' interests, and communicating with clients) with a higher and more specific standard. The detailed rules sit in PRIN 2A, and the FCA's final guidance is FG22/5.
The three cross-cutting rules
The cross-cutting rules describe how firms must behave in everything they do for retail customers. Each has a direct read-across to advice conversations:
- Act in good faith. Honest, fair and open dealing — no pressure, no exploiting a customer's lack of knowledge or their circumstances.
- Avoid causing foreseeable harm. If an adviser can reasonably foresee that a recommendation or a gap in the explanation could harm the customer, the firm is expected to prevent it.
- Enable and support customers to pursue their financial objectives. The conversation should start from what the customer is trying to achieve, in their words, and stay anchored to it.
The four outcomes — and what they sound like on a call
The four outcomes give the Duty its structure. Most firms organise their monitoring and their board reporting around them. Here is how each one shows up in an advice conversation:
| Outcome | What the FCA expects | What it sounds like on a call |
|---|---|---|
| Products & services | Products are designed for the needs of an identified target market and distributed to it. | The adviser explores needs, objectives and alternatives before recommending anything, and the recommendation is tied back to them. |
| Price & value | The price the customer pays is reasonable relative to the benefits. | Fees, charges and long-term costs — such as interest roll-up or early repayment charges — are explained, not assumed. |
| Consumer understanding | Communications equip customers to make effective, timely and properly informed decisions, and firms test that they do. | Plain language, key risks covered, and the customer's understanding checked — ideally in their own words. |
| Consumer support | Support meets customers' needs, with no unreasonable barriers ("sludge"). | The adviser notices when someone needs more support, adapts, and leaves clear next steps. |
Each outcome can be turned into specific, observable rules for a call. We cover how in writing compliance rules an AI can check.
Vulnerable customers under the Duty
The Duty expects firms to consider the needs of customers with characteristics of vulnerability throughout, and to make sure those customers get outcomes as good as everyone else's. The FCA's guidance on the fair treatment of vulnerable customers, FG21/1, groups the drivers of vulnerability into four areas: health, life events, resilience and capability.
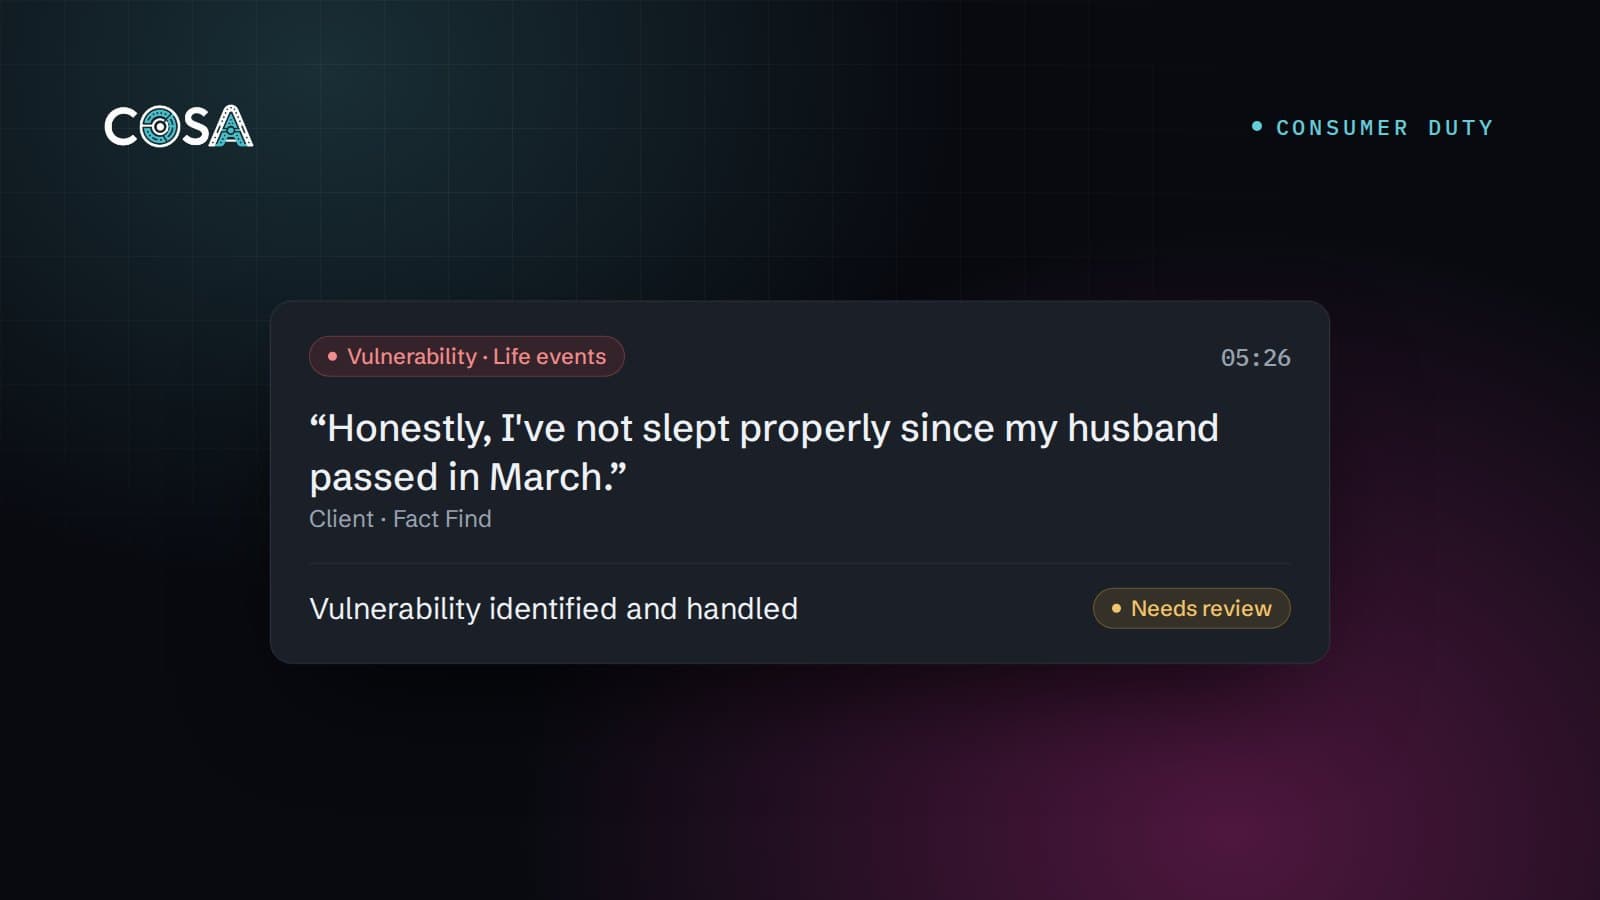
Vulnerability rarely announces itself. It tends to surface in passing — a bereavement mentioned in the middle of a fact find, a son answering questions on his mother's behalf — which is exactly why it is so often missed by a sample. Our guide to identifying vulnerable customers on calls works through each driver with examples.
Governance: monitoring and the annual board report
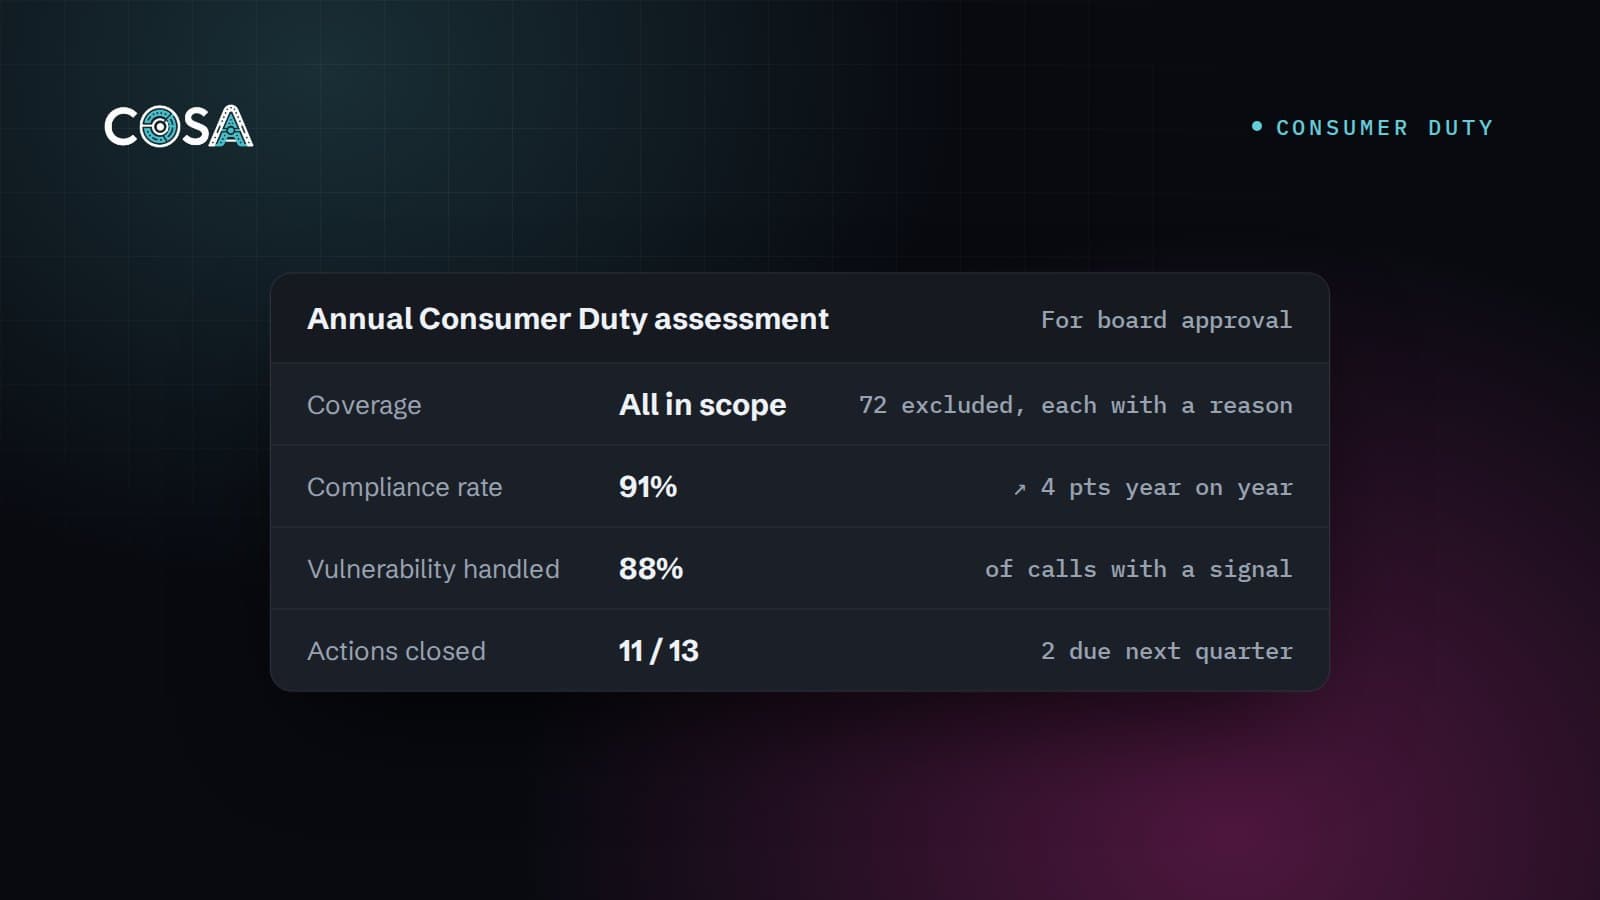
Firms must monitor the outcomes their customers receive, identify where particular groups are getting poor outcomes, and act. At least once a year, the governing body must review and approve an assessment of whether the firm is delivering good outcomes — and agree what will be done where it isn't. The FCA also expected firms to appoint a board-level Consumer Duty champion.
That assessment is only as strong as the evidence behind it. Reports that describe processes rather than outcomes, or rely on thin MI, give a board little to challenge. We set out a practical structure in what to put in your Consumer Duty board report.
Where advice firms struggle to evidence outcomes
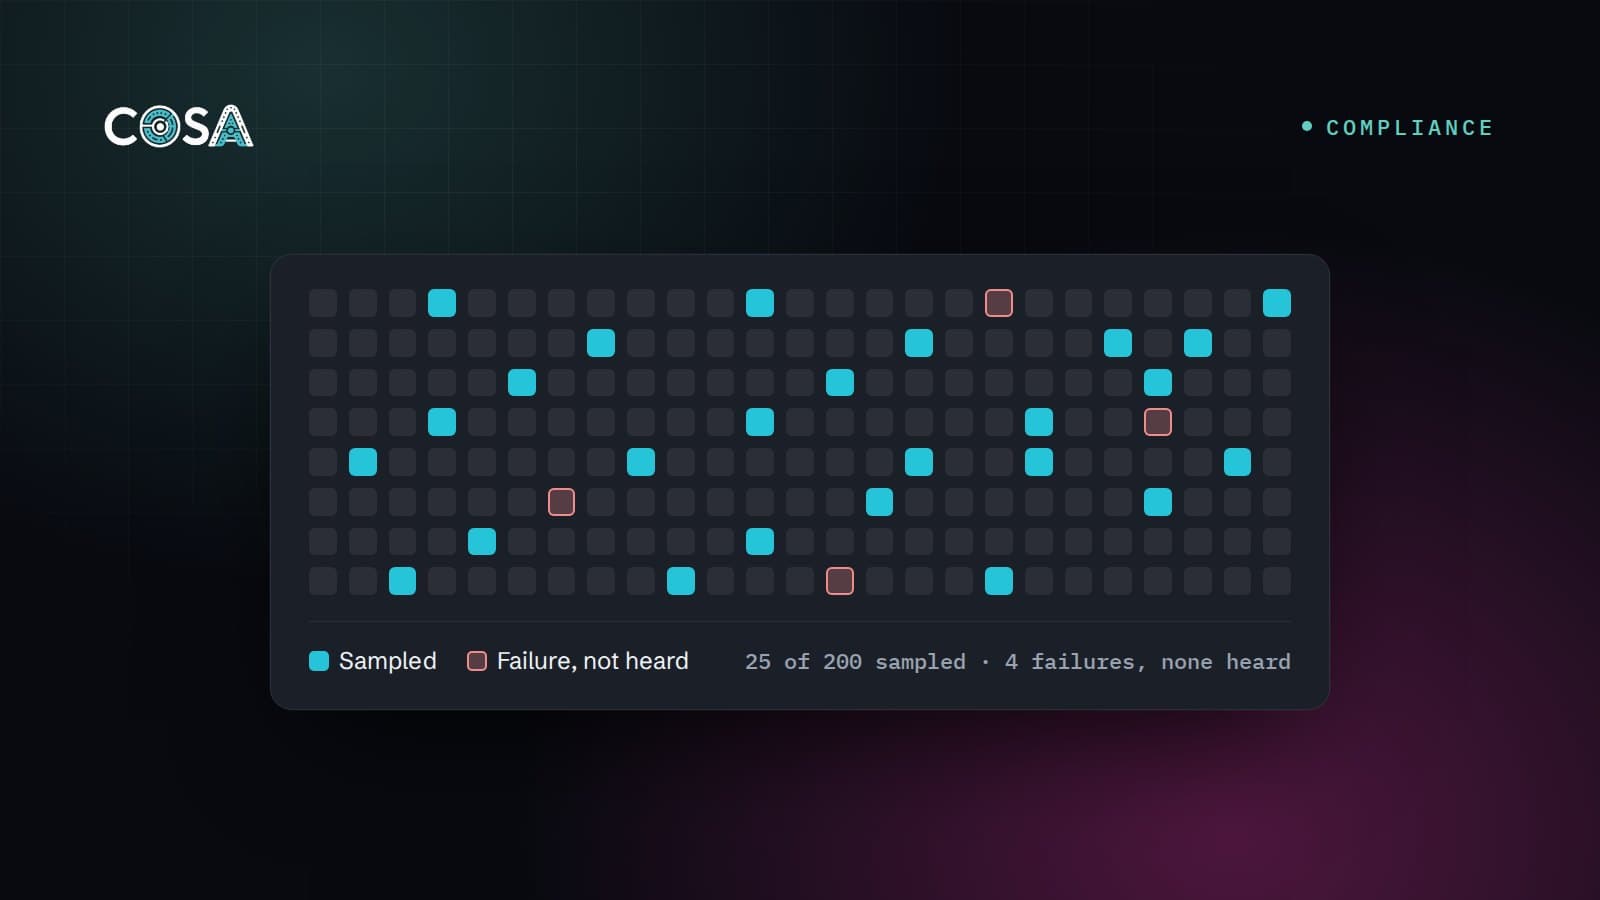
- Small samples. Manual QA typically hears a small fraction of calls, so problems that affect one call in fifty are easily missed. We did the maths in how many calls should you review?
- Activity instead of outcomes. "Calls reviewed" and "files checked" measure effort. The board needs to know what customers experienced.
- Inconsistent judgement. Two reviewers can score the same call differently, which makes trends hard to trust.
- Vulnerability data that doesn't join up. Flags live in notes, not in MI, so outcomes for vulnerable customers can't be compared with everyone else's.
- No closed loop. Findings don't lead to coaching, rule changes or remediation that anyone can point to.
Turning client calls into Consumer Duty evidence
Calls are where advice actually happens, so they are where much of the outcome evidence lives. A practical approach looks like this:
- Write rules for each outcome. Exact wording where it matters (a recording notice, a risk warning), and the topics that must be covered however they are phrased (alternatives, roll-up, the customer's objectives).
- Decide which calls are in scope — and log the rest. A call-selection policy (call types, minimum length, answered calls) makes coverage explicit, and a reason for every excluded call makes it defensible.
- Assess every in-scope call. Automated first-pass review applies the same rules to every call and brings the ones that need judgement to your team, with the quote and the reasoning.
- Keep people in charge. Reviewers confirm or override results, and the original verdict stays on record.
- Report by outcome. Compliance rate by outcome, call type and adviser; the rules most often missed; vulnerability flags and how they were handled.
- Close the loop. Coaching, remediation and rule changes, each with an owner — and the next period's MI to show whether they worked.
This is the approach COSA is built around: every in-scope call assessed against your own rules, every verdict evidenced, and MI your board can use. See how COSA supports the Consumer Duty.
A ten-point Consumer Duty checklist for advice firms
- Your advice process starts from the customer's objectives, recorded in their words.
- Alternatives are discussed, and the reasons for discounting them are recorded.
- Costs, charges and long-term effects are explained on every relevant call.
- Key risks are covered, and understanding is checked — not assumed.
- Signs of vulnerability are identified, and the adviser's response is recorded.
- You can say which calls your monitoring covered, and why any were excluded.
- Findings are consistent from reviewer to reviewer, and overrides are recorded.
- MI reports outcomes by outcome area, customer group and adviser.
- Every finding has an owner and an action, and you track whether it worked.
- The board sees, challenges and approves the assessment at least once a year.
This article is general information, not legal or regulatory advice. Always refer to the FCA Handbook and the FCA's own guidance for your firm's obligations.